How to Compare Rhode Island Coastal Towns Before Buying a Home
Key Takeaways
- Coastal appeal matters, but total ownership cost matters more.
- Flood mapping, elevation, insurance availability, and drainage should be reviewed before an offer is made.
- Town-by-town comparisons should include services, travel patterns, seasonal activity, and maintenance demands.
- Recent closed sales are more useful than asking prices when evaluating value.
- A simple scorecard can keep a home search focused on practical priorities.
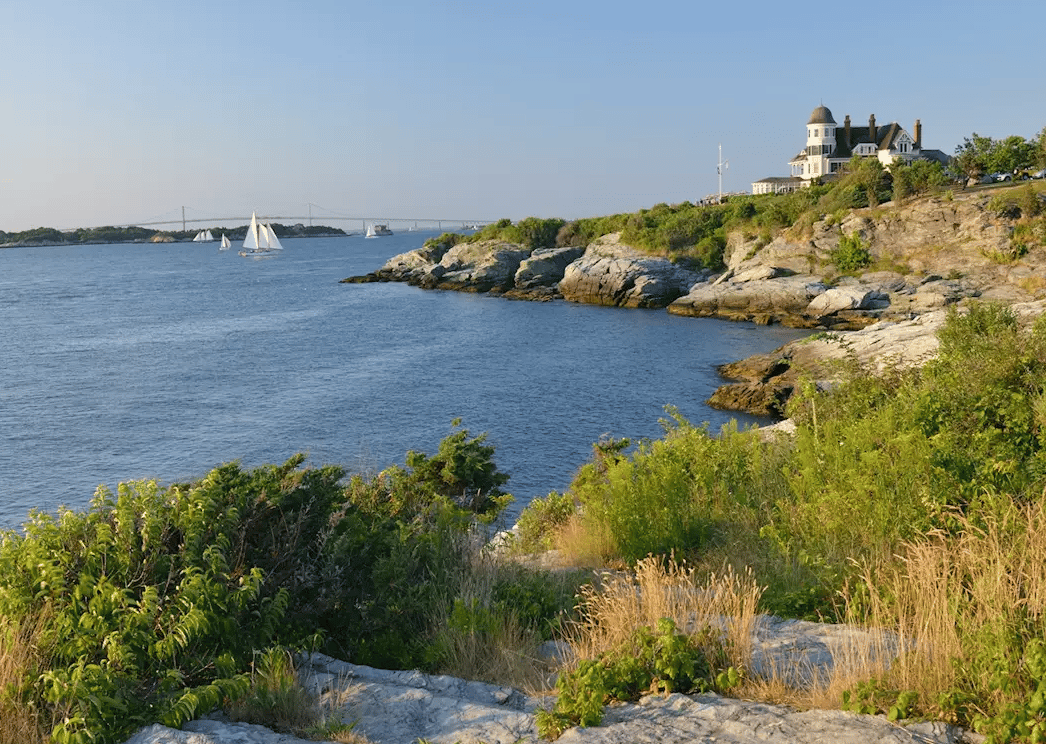
Buying near the Rhode Island shoreline can mean waking up close to beaches, marinas, salt ponds, and historic village centers. It can also mean weighing factors that are less visible during a sunny showing, including insurance, flood exposure, seasonal traffic, maintenance, and access to daily services. The best coastal town is not necessarily the one with the most dramatic water view. It is the one that fits how you plan to live, travel, and manage the property over time.
For buyers starting their search in South County, Homes for Sale in Narragansett RI can be explored through Edge Realty’s searchable local listings page. Edge Realty serves Rhode Island, Connecticut, and Massachusetts, with offices in Narragansett and Newport, making its neighborhood-focused search tools useful for comparing cottages, condos, year-round homes, and waterfront properties in Narragansett and nearby coastal communities.
Start With the Coastal Lifestyle You Actually Want
Rhode Island’s coast offers very different settings within a relatively small area. One buyer may want a walkable beach neighborhood with restaurants and summer energy. Another may prefer a quieter road near a pond, harbor, or conservation area. A household commuting several days each week may prioritize route access, while a second-home buyer may care more about property security and easy upkeep.
Before comparing listings, write down the property’s main purpose. Is it a primary residence, a weekend retreat, a retirement home, or a rental-capable investment? That answer should shape every later decision. A home that works beautifully for July visitors may feel inconvenient in January if groceries, medical appointments, winter road access, and community life are important to you.
Build a Coastal Town Scorecard
Give every town or property a score from one to five in the categories below. The purpose is not to produce a perfect number. It is to prevent one attractive feature, such as a beach view, from overwhelming the rest of the decision.
- Purchase price and property type:Compare similar homes, such as cottages with cottages and condos with condos, rather than treating every listing as interchangeable.
- Insurance and flood exposure:Obtain estimates early, especially for homes near the ocean, bays, ponds, or low-lying roads.
- Condition and maintenance:Consider roof age, siding, windows, drainage, heating equipment, decks, and foundation condition.
- Daily convenience: Look at grocery access, health care, schools, libraries, restaurants, and municipal services.
- Travel time: Test routes to work, train service, airports, family, and other places you visit often.
- Seasonal rhythm: Decide whether summer traffic, visitors, and activity are benefits or drawbacks.
- Rental feasibility: Confirm local rules, association restrictions, operating costs, and realistic demand before relying on rental income.
Compare the Full Cost of Ownership
The list price is only the entry point. A complete monthly budget should include principal and interest if financed, property taxes, homeowner’s insurance, possible flood insurance, utilities, association fees, and a reserve for repairs. Coastal homes may require more frequent attention because wind, moisture, salt air, and seasonal weather can affect exterior materials and mechanical systems.
Ask for utility history when available, review maintenance records, and budget for items that may not appear in a listing description. These can include drainage improvements, tree work, exterior painting, roof repairs, septic or well service, deck upkeep, and storm preparation. A less expensive house can become the costlier option if it needs immediate work or carries substantially higher insurance costs.
Check Flood Maps, Elevation, and Site Conditions
Never assume two homes near the water carry the same risk. Elevation, the placement of the structure, the road leading to it, nearby drainage, and the type of shoreline can all affect a property’s exposure. Review the current flood-zone designation, ask about known past flooding or water intrusion, and inspect where electrical panels, heating systems, and finished living areas are located.
The state’s guidance on FEMA flood zones and insurance explains why a high-risk flood designation can affect mortgage requirements, building standards, and premiums. If an elevation certificate exists, request it. If it does not, ask an insurance professional what information is needed to provide a meaningful quote. Standard homeowner’s policies generally do not cover flood damage, so flood coverage should be evaluated separately.
Also, check whether future improvements could be constrained by local zoning, coastal regulations, setbacks, or floodplain rules. A buyer who plans to add living space, raise a structure, rebuild a deck, or make major site changes should investigate those plans before closing rather than assuming they will be easy later.
Look Beyond the Beach on Your Visits
Visit each target area more than once. A Saturday afternoon in peak season can reveal parking pressure, beach traffic, and restaurant activity. A weekday in the off-season can show whether the neighborhood still feels convenient and comfortable when visitors are gone. Drive the routes you would actually use, including trips to shopping, appointments, schools, and work.
Pay attention to practical details: street lighting, sidewalks, road width, parking, noise, cellular service, and access during poor weather. These details influence everyday enjoyment and can affect the future pool of buyers when it is time to sell.
Read the Market at the Town Level
Statewide housing reports provide context, but they cannot tell you how a particular street or coastal pocket is performing. Compare recent closed sales with similar square footage, condition, lot characteristics, and proximity to water. Separate waterfront homes from inland homes, and distinguish turnkey renovations from properties that need substantial work.
Pay close attention to days on market, price changes, and the gap between asking and closing prices. These signals can help you understand whether a seller’s expectations align with recent transactions. Interest rates, insurance costs, and repair needs can also change the effective price a buyer can afford.
Match the Town to Your Buyer Profile
Year-Round Residents
Prioritize winter convenience, local services, school needs, reliable access, and commute patterns. A lively seasonal area can still be a strong fit, but only if the off-season lifestyle works for your household.
Second-Home Buyers and Retirees
Focus on maintenance, security, travel time, walkability, medical access, and whether the home can be left vacant without creating unnecessary concerns. Condos or smaller homes may offer a lower-maintenance path, although association rules and fees should be reviewed carefully.
Rental Investors and Waterfront Buyers
Rental buyers should verify municipal and association rules before projecting income. Waterfront buyers should place insurance, erosion, access, elevation, maintenance, and long-term property stewardship at the top of the scorecard.
Buyer’s Research Checklist
- Set a maximum purchase price and an all-in monthly housing budget.
- Request homeowners and flood insurance estimates before finalizing an offer.
- Review flood maps, elevation information, zoning, and permit history.
- Compare recent closed sales in at least three nearby communities.
- Visit at different times of day and, when possible, in different seasons.
- Inspect the roof, foundation, drainage, lower level, heating system, and exterior materials.
- Confirm taxes, utilities, septic or well responsibilities, and rental restrictions.
Choose the Best Fit, Not Just the Best Photo
A Rhode Island coastal home should support your budget, lifestyle, risk tolerance, and future plans. Choose the town and property that perform well across the categories that matter most to you. When the numbers, condition, location, and daily experience all align, the shoreline view becomes even more rewarding.